What Is a Reverse Mortgage? What Every Canadian Homeowner Should Know Right Now
IndiBrick Editorial
IndiBrick Financial
By Mudit Chhura | Co-Founder, IndiBrick | Read Time: 9 Mins
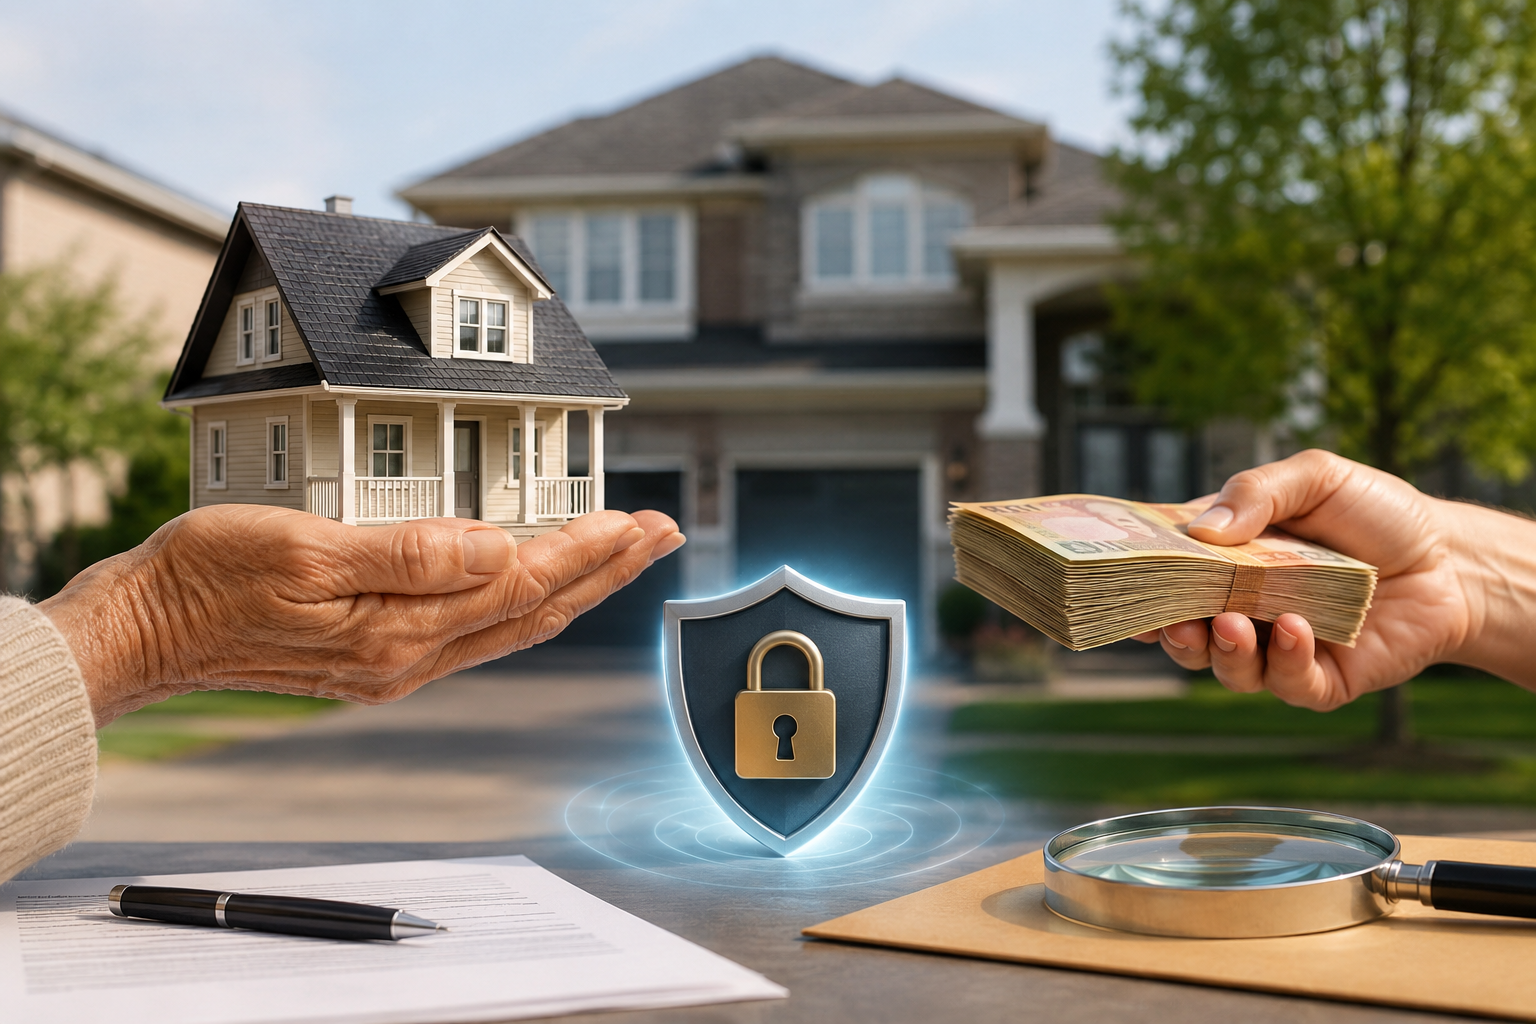
A story making the rounds in Ontario this week should make every homeowner pause. A Brampton woman who had already paid off her home reportedly discovered that a $405,000 reverse mortgage had been registered against her title, one she says she never applied for or authorized. According to public reporting, the case involves a third-party broker and allegations of forged electronic signatures, and it remains under investigation with nothing yet determined by a court.
Whatever the outcome, the case has put two words on the minds of Canadian homeowners searching Google right now: reverse mortgage. Search interest in "what is a reverse mortgage" is up sharply this month, alongside a surge in related searches for mortgage preapproval, mortgage payment calculations, and fixed-rate mortgage options. This guide answers the questions homeowners are actually asking, what a reverse mortgage is, how it differs from a traditional mortgage, how to protect your title from fraud, and how to get properly preapproved for whatever financing path is right for you.
What Is a Reverse Mortgage?
A reverse mortgage is a loan available to Canadian homeowners, typically aged 55 and older, that allows them to borrow against the equity in their home without selling it or making regular monthly mortgage payments. Instead of paying the lender every month, interest accumulates and is added to the loan balance over time. The loan, plus accumulated interest, is repaid when the homeowner sells the property, moves out permanently, or passes away.
Reverse mortgages can provide real value for retirees who are equity-rich but cash-flow-limited, giving them access to funds for healthcare costs, home repairs, or day-to-day living expenses without giving up homeownership. But because no payments are made along the way, the loan balance grows every year, and the product carries requirements most other mortgage products do not.
- Independent legal advice is required by law in Canada before a reverse mortgage can be approved
- Homeowners remain responsible for property taxes, home insurance, and property upkeep
- Interest rates on reverse mortgages are typically higher than on a standard fixed-rate mortgage
- The loan balance compounds over time, which can significantly reduce the equity left for the homeowner or their estate
Why the Darlene Early Case Matters to Every Homeowner
Regardless of how the specific allegations in this case are ultimately resolved, it has surfaced a broader and well-documented risk that consumer advocates have warned about for years, title fraud and unauthorized reverse mortgage registrations. According to legal experts covering the story, the alleged fraud involved a broker who has separately been charged with fraud in an unrelated matter, and electronic signing records that reportedly showed activity from locations the homeowner says she was never in.
This is not the first time Canadian consumer protection groups have flagged reverse mortgage and title fraud risks, particularly targeting seniors. Fraudsters can, in rare but real cases, register liens or mortgages against a property without the owner's knowledge, especially when identity verification and signing processes are handled remotely rather than in person.
A mortgage-free home is not automatically a fraud-proof home. Title fraud does not care whether you have a balance owing, it targets equity, and a fully paid-off house is often the biggest target of all.
How to Protect Yourself From Title and Mortgage Fraud
You do not need to be facing a reverse mortgage decision to be at risk. Every homeowner, especially those who own their home outright, should take a few basic protective steps.
- Check your property title and mortgage statements periodically for any new registrations, liens, or mortgages you did not authorize
- Consider title insurance, which can help protect against forgery, fraudulent electronic signatures, and unauthorized registrations against your property
- Be cautious of any mortgage or home equity product that is arranged entirely remotely with no in-person verification
- Work only with licensed, verifiable mortgage professionals, and confirm their licensing directly through your provincial regulator if you are ever unsure
Not Sure What Financing Actually Fits Your Situation?
Run your numbers through our affordability calculator to see real, personalized estimates before you speak with anyone.
Check Your AffordabilityReverse Mortgage vs. Traditional Fixed-Rate Mortgage
For homeowners weighing their options, it helps to see the two products side by side.
| Feature | Reverse Mortgage | Traditional Fixed-Rate Mortgage |
|---|---|---|
| Monthly payments | Not required | Required |
| Minimum age | Typically 55+ | None |
| Interest rate | Generally higher | Generally lower |
| Equity over time | Decreases as interest compounds | Increases as principal is paid down |
| Independent legal advice required | Yes, mandatory in Canada | Not typically required |
How to Get Preapproved for a Mortgage the Right Way
Whether you are exploring a reverse mortgage, a first purchase, or a renewal, mortgage preapproval is the step that gives you real numbers instead of guesses. A proper preapproval typically involves the following.
- A review of your income, credit history, and existing debt to calculate your maximum affordability
- A rate hold, which protects you from rate increases for a set period while you shop for a home
- An accurate mortgage payment calculation based on current rates, your down payment, and your amortization period
- A clear picture of your maximum purchase price, so you are shopping with confidence rather than hope
This is also where working with a broker instead of a single bank matters. A broker can generate a mortgage quote across multiple lenders at once, rather than limiting your preapproval to one institution's rate sheet and criteria.
See What You Could Be Preapproved For
Get a clear, accurate estimate of your affordability and payments before you start shopping for a home or renewal.
Calculate Your Mortgage PaymentFrequently Asked Questions About Reverse Mortgages and Title Fraud
What is a reverse mortgage in Canada?
A reverse mortgage is a loan available to homeowners, typically aged 55 and older, that allows them to borrow against their home equity without making monthly payments. The loan and accumulated interest are repaid when the homeowner sells the property, moves out permanently, or passes away.
Can someone put a reverse mortgage on my home without my knowledge?
While rare, title fraud and unauthorized mortgage registrations do occur, particularly through identity theft, forged signatures, or compromised remote verification processes. Regularly checking your property title and mortgage statements, along with considering title insurance, are two of the most effective ways to protect yourself.
How do I calculate my mortgage payments?
Mortgage payments are calculated based on your loan amount, interest rate, and amortization period. An online mortgage calculator or a preapproval conversation with a broker can give you an accurate, personalized payment estimate based on current rates.
Is a fixed-rate mortgage better than a reverse mortgage?
They serve different purposes and different life stages. A fixed-rate mortgage is used to purchase or refinance a home with regular payments that build equity over time. A reverse mortgage is designed for older homeowners who want to access existing equity without monthly payments, and it reduces equity over time rather than building it.
How do I get an accurate mortgage quote?
The most accurate mortgage quotes come from comparing multiple lenders based on your actual income, credit profile, and property details, rather than a single bank's advertised rate. A mortgage broker can generate quotes across several lenders at once for direct comparison.
The Bottom Line
Reverse mortgages can be a legitimate and valuable tool for the right homeowner, but they come with real trade-offs, higher interest costs, mandatory legal advice, and equity that decreases rather than grows over time. And as recent reporting reminds us, every homeowner, mortgage-free or not, should treat their property title with the same vigilance they treat any other major financial asset.
Whether you are exploring a reverse mortgage, working toward a first purchase, or simply want an accurate mortgage quote before your next renewal, the right first step is the same: get real numbers from someone who can compare your options across the full market, not just one institution's rate sheet.
Get Clarity Before You Decide
Whether it is a reverse mortgage, a purchase, or a renewal, know your real numbers before you commit to anything.
Book a Free Strategy Call Try the CalculatorMortgage Payment Scenarios
Model your monthly payments at different rates.
1. Purchase Details
2. Mortgage Details
3. Property & Closing
Your Monthly Payment
$3,251
Monthly Breakdown (Est)
Stress Test Qualification
To qualify for this mortgage at the 6.29% stress test benchmark, you will need an approximate household income of $140,358 / year.
About the author
IndiBrick Editorial
IndiBrick Editorial Team
Written and fact-checked by the IndiBrick editorial team. Mortgages are brokered through Pineapple Financial Inc. (FSRA #12830).
Related analysis
Mortgage
Bank of Canada Warns Tariffs Could Slash Q4 Growth in Half, And Toronto Delinquencies Are Already Rising
Mortgage
Odds of a December Bank of Canada Rate Hike Are Rising, Here's Why
Mortgage
US Escalates Canada Trade War With New Bans and Tariffs: What It Means for GTA Buyers and Self-Employed Borrowers
Ready to act?
Turn this insight into a funded deal.
Book Call